
Principal®
- Rating
- 4.7
- Downloads
- 1.00M
- Content Rating
- Everyone
Principal® - Screenshots
Pros
- Simple interface makes daily planning quick and easy.
- Useful reminders help keep important tasks visible.
- Supports organized routines for work
- study
- or personal goals.
- Lightweight design runs smoothly on most modern devices.
- Can help reduce missed deadlines and forgotten responsibilities.
Cons
- Some advanced features may require a paid subscription.
- Customization options may feel limited for power users.
- Notification settings can become overwhelming with many tasks.
- May take time to build a consistent planning habit.
- Not ideal for users seeking detailed project-management tools.
Principal® - Description
- App Name
- Principal®
- Package Name
- gokart.com.principal
- Developer
- Principal Financial Group, Inc.
- Category
- Finance
- Last Updated
- Mar 1, 2019
- Version
- 4.0.146
Managing money from a phone sounds simple until several people in the same household need to stay aligned. One person may be checking retirement progress, another may be reviewing workplace benefits, and someone else may only want a quick look at an account before making a decision. I found Principal® most useful in that kind of personal-finance routine: it puts Principal-related financial information within reach without turning the phone into a full budgeting command center.
Developed by Principal Financial Group, Inc., this free finance app is aimed at people who already use Principal services and want a more convenient way to keep up with their financial goals while away from a computer. It is available for everyone from an age-rating perspective, has passed the one-million-install mark, and holds a 4.7 average from roughly forty-four thousand ratings. Those figures suggest a well-established app, but they do not remove the need to think carefully about who should use it, what each household member is actually entitled to see, and when a browser or another finance tool would be more appropriate.
How Principal® fits into a shared household routine
Imagine a couple sitting at the kitchen table after work. One person wants to review a workplace retirement account, while the other is trying to remember whether a recent financial task was completed. Opening a phone app is more practical than finding a laptop, navigating a website, and waiting for a larger planning session. In this scenario, the app works as a quick checkpoint rather than a replacement for a household meeting.
I like that distinction because financial apps can encourage people to confuse access with coordination. Seeing an account on a screen does not automatically mean every person in the household should use the same login, make changes for someone else, or treat a glance at a balance as a complete plan. Principal® is better approached as an individual account tool that can support a shared conversation when the account holder chooses what to discuss.
A realistic use case is a monthly review. The account owner opens the app privately, checks the information that matters, and then brings only the relevant points to a partner: whether a goal still feels realistic, whether a contribution decision needs attention, or whether a follow-up with an employer or financial professional is necessary. That workflow keeps the app useful without turning a shared device into an open financial record.
On a family tablet or a phone passed between household members, I would be more cautious. A device can be shared while an account should not be. The convenience of leaving an app available is outweighed by the risk of another person seeing private financial information. I would sign out when appropriate, use the device’s normal security protections, and avoid treating a common household screen as a common account.
What the app is good at during everyday check-ins
The strongest role here is quick awareness. If you already have a relationship with Principal, a mobile view can make it easier to keep financial goals in mind instead of postponing every check until you are at a desktop. That matters for people who prefer short, regular check-ins over long sessions filled with paperwork.
I would use it before a scheduled household conversation, not during every conversation. First I would review the account privately, note the questions that need discussion, and then talk through those questions without passing the phone around unnecessarily. This small habit improves privacy and also keeps the conversation focused on decisions rather than on scrolling through screens.
The app is less suitable as a shared household ledger. It is not the tool I would choose to record rent, groceries, utilities, debts, or a child’s allowance alongside an account held through Principal. For those tasks, a dedicated budgeting app, spreadsheet, or banking tool may offer a clearer household view. Principal® has a narrower purpose, and that narrowness is useful when you respect it.
Setting boundaries before anyone else touches the phone
The first setup decision is not a button inside the app; it is deciding whose account the app represents. If one person owns the Principal relationship, that person should remain the person responsible for access and account decisions. A partner can participate in planning without automatically becoming another user of the same signed-in session.
That boundary is especially important on devices with multiple profiles or users. I would avoid saving access details in a place where children, guests, or coworkers can reach them. I would also be careful with notifications, because a message appearing on a lock screen can reveal more than intended even when nobody opens the app.
Households should also agree on what “checking together” means. It might mean the account holder reads a general update aloud. It might mean both adults sit together while the owner navigates. It should not mean copying passwords into a family chat or leaving the account open for convenience. These are ordinary habits, but they make a bigger difference than installing another finance app.
For a shared device, I would create a simple routine: open the app only when the account owner is present, review the needed information, close the session, and return the device to its normal shared use. If the phone is personal, the same principle still applies when another household member borrows it. Financial privacy should survive casual device sharing.
Coordinating goals without confusing account access
Principal® can support coordination when the household separates information from responsibility. The account owner can bring figures, questions, and priorities into a conversation, while the other person helps evaluate the wider household impact. For example, a couple might discuss whether a planned contribution fits alongside an upcoming home repair, but the person who owns the account remains the one who reviews and confirms account-specific actions.
This approach also helps prevent a common mistake: making a financial change simply because another person saw a number and reacted to it. A balance or progress indicator needs context. It may relate to a long-term goal, a workplace arrangement, or a decision that should be considered with other resources. I would never treat a quick mobile glance as a complete recommendation.
My practical tip is to keep a short list of questions outside the app. Write down what you want to understand before opening the account, then close the app once those questions are answered. This reduces aimless browsing and makes shared discussions less likely to expose unrelated details. It is a small workflow, but it turns the app from a passive balance viewer into a more disciplined checkpoint.
Another useful distinction is between coordination and delegation. A household may coordinate retirement planning, but that does not mean one person should operate another person’s account. If someone needs formal authority or a different kind of access, that should be handled through the appropriate financial process rather than improvised with a shared phone.
Age, trust, and the meaning of an everyone rating
The app carries an Everyone content rating, which makes sense for a mainstream financial tool rather than an entertainment product. Still, an age rating is not the same as permission to view or manage financial information. A child may be able to encounter the app on a family device, but that does not make the child an appropriate account user.
For teenagers learning about money, I would use Principal® as a teaching aid only through a supervised conversation. An adult could explain broad ideas such as saving for a long-term goal or reviewing workplace benefits without handing over credentials or exposing private account details. The educational value comes from the discussion, not from letting a young person explore an adult account independently.
Trust matters just as much among adults. Partners may share finances closely, but relationships and account permissions are not identical. Someone might be comfortable discussing a goal while still wanting the account itself to remain private. I think the app works best when households make that distinction explicit instead of assuming that shared finances require unrestricted phone access.
This is also where the app’s focused design can be a strength. It does not need to become a family social space to be useful. A quiet, individual check-in followed by a deliberate conversation is often safer and clearer than giving every household member casual access to every financial screen.
Where it sits beside banking and budgeting alternatives
Compared with a bank’s mobile app, Principal® is more specialized. A banking app is usually the natural place to review everyday spending, move money between common accounts, or check transactions. Principal’s app makes more sense when your question is tied to your Principal relationship and longer-term financial goals rather than today’s grocery purchase.
Compared with a budgeting app, it also offers a different perspective. Budgeting tools are designed around categories, recurring bills, spending limits, and household cash flow. I would choose one of those when the main challenge is coordinating who pays for what. I would choose Principal® when I need a mobile window into the financial information connected with Principal.
A desktop browser can still be the better option for complicated work. If I were comparing several documents, trying to understand a detailed workplace benefit, or preparing for a serious financial discussion, the larger screen and calmer environment would be preferable. The phone app is convenient, but convenience is not the same as depth.
That trade-off is worth remembering when deciding whether to install it. The app is not a universal replacement for banking, budgeting, document storage, or professional advice. Its value comes from reducing friction around the Principal-specific check-in. People who want one dashboard for every household account may find a broader financial aggregator more suitable, while accepting that broader tools bring their own privacy and organization considerations.
What to expect from the current app experience
The current version is 4.0.146, and the app has been available since March 1, 2019. I mention that because it feels like a mature mobile product rather than a brand-new experiment. The large installed base and strong average rating reinforce that impression, although individual experiences can still vary with account type, device, sign-in conditions, and the kind of task being attempted.
The app is free to download, which removes an obvious barrier for existing Principal customers who want mobile access. Free does not mean it replaces the underlying financial relationship or makes every financial decision simple. I would still read each screen carefully and avoid making a rushed choice merely because the information is easier to reach.
One friction point with any finance app is that the most important moment can be the least convenient one: signing in when you are in a hurry, checking information on a borrowed device, or trying to discuss an account while several people are watching. I would plan around that rather than blaming the app for every boundary. Use a private device when possible, keep the session focused, and move complex questions to a more suitable setting.
I also would not judge the app solely by how quickly it opens. A finance tool earns its place by helping me form a better habit. If it prompts a useful monthly review, helps me remember a goal, or gives me a starting point for a conversation, it is doing its job. If I only open it impulsively to watch a number move, the app is not solving the underlying planning problem.
Who should install it, and who should skip it
I would recommend Principal® to an existing Principal customer who wants a convenient mobile check-in and understands that the app is centered on that relationship. It is particularly sensible for someone who travels, works away from a desk, or prefers short reviews throughout the month. It can also help a couple coordinate long-term priorities, provided the account owner controls access and shares information intentionally.
I would be less enthusiastic for someone seeking a complete household budget. If your priority is tracking bills, splitting expenses, monitoring several banks, or teaching children through a shared money dashboard, another category of app will probably fit better. Installing Principal® will not remove the need for those tools.
I would also skip it as a first choice if you do not have a Principal-related financial need. A high rating and a substantial install base do not make a specialized app useful to everyone. The right question is not whether the app is popular; it is whether its account-focused purpose matches the task you actually want to complete.
For older relatives or less technical household members, I would introduce it slowly. A trusted adult can help with the first sign-in and explain the difference between viewing information and taking action, but should avoid keeping another person’s credentials. If the user cannot comfortably recognize when a screen requires careful attention, a guided desktop session may be safer than unsupervised phone use.
My household verdict
After looking at it through a shared-device lens, I see Principal® as a useful personal finance companion with a clear boundary: it belongs to the individual account holder, even when the financial goals affect an entire household. It makes mobile check-ins easier, supports better preparation for money conversations, and avoids pretending to be a complete family budget manager.
My favorite way to use it would be a private review followed by a short, planned discussion. I would check the relevant information, write down questions, close the session, and then talk with the people affected by the goal. That workflow keeps the app practical while protecting account boundaries.
The main limitation is not that it lacks every household feature; it is that users may expect a specialized account app to coordinate an entire financial life. It cannot replace a budget, a shared calendar, a bank app, or thoughtful planning. Once that expectation is set correctly, the experience becomes much more sensible.
For existing Principal customers, the free price and mobile convenience make it worth trying, especially if quick access helps maintain a regular financial habit. For everyone else, I would choose a tool built around the actual job: daily banking for transactions, budgeting software for shared expenses, or a larger screen for complex research. My recommendation is to use Principal® as a private checkpoint that improves household conversations, not as a communal account window.
FAQ
What is Principal® and what can I use it for?
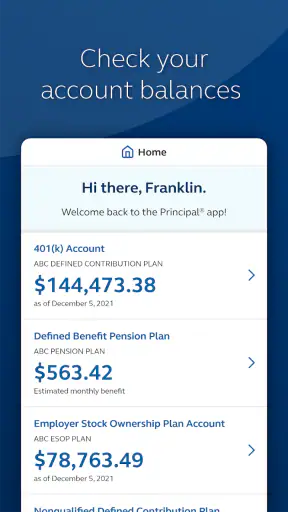
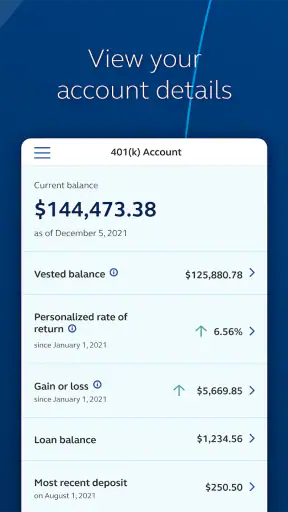
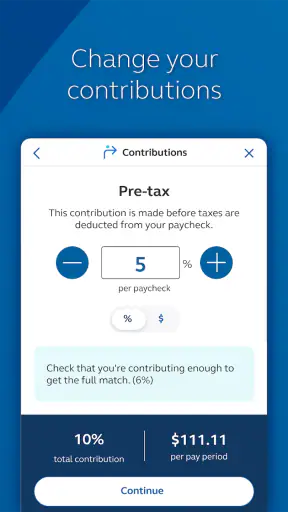
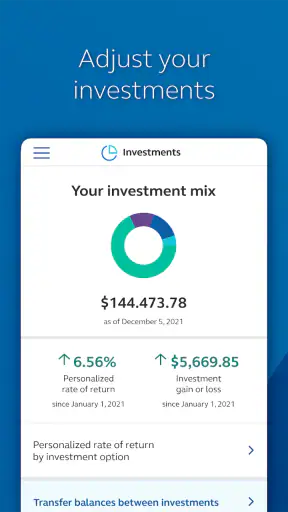
Principal® is a digital platform designed to help users access and manage the services offered by Principal. Depending on your location and account type, the app may provide tools for viewing account information, checking balances or investments, reviewing transactions, accessing documents, and managing selected personal details. Available features can vary by country, product, and eligibility, so you should confirm that the services you need are supported before downloading.
Do I need a Principal® account to use the app?
In most cases, you need an eligible Principal account and valid login credentials to access the app’s main features. New users may be able to register through the application, although the process can require personal information, identity verification, and details connected to an existing Principal product. Some public information may be available without signing in, but account management tools generally require authentication.
Is Principal® safe to use for personal and financial information?
Principal® is intended to protect account access through security measures such as encrypted connections, login authentication, and additional verification options where available. However, no online service is completely risk-free. Use the official app store listing, keep your operating system updated, avoid sharing passwords or verification codes, and never sign in through links received from suspicious messages or unofficial websites.
Is Principal® free to download and does it charge fees?
The Principal® app is generally available as a free download from the official Android or iOS store, but downloading the app does not necessarily mean that every service is free. Fees, investment costs, account charges, or product-specific expenses may still apply according to your agreement with Principal. Review the terms connected to your account and check with Principal if you are unsure about any charge.
What should I do if I cannot log in or the app is not working?
If Principal® will not open or you cannot sign in, first check your internet connection, update the app, and confirm that your device meets the current operating-system requirements. Make sure your credentials are entered correctly and use the official password-recovery option if necessary. Avoid repeatedly guessing passwords, and contact Principal support through its official website or app if the issue continues.


